Table of Contents
- Understanding Permanent Impairment vs. Permanent Disability
- Gather Medical Evidence for Personal Injury Claim
- How to Document Long-Term Injury Effects
- Maximum Medical Improvement and Impairment Rating Assessment
- Independent Medical Examination in Personal Injury Cases
- Calculating Permanent Injury Settlement Value
- Common Mistakes to Avoid When Proving Permanence
- Frequently Asked Questions
Last Updated: October 21, 2026
Understanding Permanent Impairment vs. Permanent Disability
Permanent impairment is a measurable loss of physical or mental function expected to last the rest of your life.
This distinction matters for your settlement. An impairment rating may document lasting loss of function, but it does not by itself determine how much money you receive, a rating does not automatically equal a specific dollar amount.
At Cummings Law, we help clients understand this difference because your settlement depends on how you prove permanent impairment affects your daily life, job, and future earning power, not just the rating.
A permanent injury increases compensation for future medical care and supports claims for lost wages and reduced earning capacity over your lifetime.
Permanent impairment is the medical finding. Permanent disability is the legal and financial impact. Your settlement reflects both.
Gather Medical Evidence for Personal Injury Claim
Strong medical evidence is the foundation to prove permanent impairment. Without documentation of lasting damage, not just temporary pain, an insurer will challenge your claim, so work from a checklist.
A practical evidence checklist for proving permanence
- Complete treatment records from every provider. ER visits, hospital admissions, surgery reports, specialist consultations, therapy notes, and follow-ups. Request the full chart, not the summary; records show continuity of care and whether symptoms persisted despite treatment.
- Diagnostic imaging and radiology reports. X-rays, MRIs, CT scans, and other imaging, including the radiologist’s written interpretation. Repeated scans showing progression (or lack of healing) support permanence.
- Objective test results. Nerve conduction studies, electromyography (EMG), blood work, and functional capacity evaluations. These tests document measurable deficits that are harder for an insurer to dismiss as subjective complaints.
- Physician prognosis and permanency opinion. A written statement identifying the injury, stating it has stabilized, and describing permanent limitations. Ask directly: “Will this heal completely?” and “What limitations will remain?” This is often the single most important document in the file.
- Impairment rating documentation. If a rating has been assigned, obtain the underlying worksheet and the specific findings that support the percentage. A rating without its basis is easy to attack.
- Work records and restrictions. Written work restrictions from your physician, your job description, and employer records showing missed days, reduced hours, or accommodations. These connect the medical finding to lost earning capacity.
- Daily-impact documentation. Symptom journals, activity logs, caregiver observations, and before-and-after comparisons. These records translate a medical impairment into real-world disability.
- Pharmacy and durable medical equipment records. Medication histories and receipts for braces, walkers, or other equipment show ongoing reliance on treatment and support future-cost claims.
Diagnostic imaging and objective findings
Objective findings, test results and imaging that prove injury exists, carry more weight than subjective complaints. A torn ligament on an MRI is objective; knee pain is subjective. Collect all images and the radiologist’s interpretation; scans showing worsening over months, or no healing after a reasonable course of treatment, strengthen your case for permanence.
Treatment history and prognosis documentation
Your treatment history shows severity and persistence: frequent visits, multiple specialists, and ongoing therapy indicate a serious condition. Document every treatment and note gaps, long gaps invite the argument that you improved. Get your physician’s written prognosis stating you will have permanent limitations; a short letter identifying the injury, stating you have reached maximum medical improvement, and listing permanent restrictions beats a vague note.
How to request and organize the records
Most providers require a signed authorization. Request records in writing, log what you requested and when it arrived, and follow up on missing items. Organize the file chronologically and by provider so your attorney and any reviewing physician can follow the treatment course quickly.
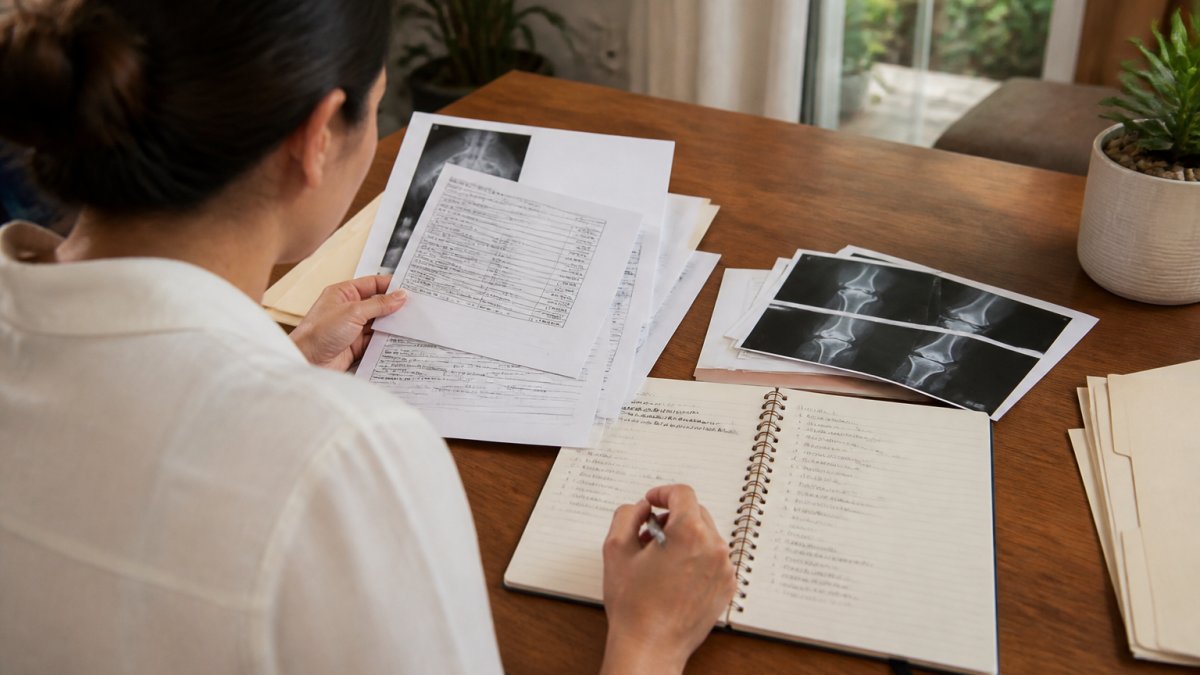
Request the full chart and the radiology reports, not just a one-page summary. The details in the treatment notes often contain the specific findings that support a permanency opinion.
How to Document Long-Term Injury Effects
Proving permanence requires showing how your injury affects you over time; medical records alone aren’t enough. Start a dated symptom and limitation journal recording daily pain levels, activities you cannot do, and specifics: “Could not lift grocery bags,” “Missed work due to pain.” Track appointments, medications, and treatments, noting what works and what doesn’t, this shows ongoing struggle, not improvement.
Functional limitations and daily activity restrictions
Functional limitations are things you cannot do anymore because of your injury, and they directly impact settlement value. List activities you did before the injury versus now:
- Before: Played tennis twice weekly
- Now: Cannot run or pivot movements
- Before: Worked full-time standing
- Now: Can only sit for two hours before pain
Be specific about timing: when did limitations appear, and have they improved, stayed the same, or worsened? Permanent impairment means they are not improving. Ask your doctor to document functional limitations in writing, describing what you cannot perform and why.
Work restrictions and earning capacity impact
Work restrictions show how your injury affects your ability to earn money, a major factor in settlement calculations. Get written restrictions from your doctor, such as:
- No lifting over 10 pounds
- No standing more than two hours daily
- No repetitive gripping motions
- Limited driving
Compare your pre-injury job duties to what you can do now. If you cannot perform your job, that strengthens your claim; if you can do a different job at lower pay, document the income loss.
Do not exaggerate limitations. Insurance companies investigate. Inconsistency between your claims and what they observe will destroy your credibility and your settlement value.
Maximum Medical Improvement and Impairment Rating Assessment
Maximum Medical Improvement (MMI) is the point where your condition has stabilized and is not expected to improve further with treatment. Ask directly: “Have I reached maximum medical improvement?” Get it in writing. (Source: Bureau of Labor Statistics)
An impairment rating is a percentage assigned by a physician measuring the extent of permanent loss of function, based on guidelines like the AMA Guides to the Evaluation of Permanent Impairment (AMA Guides | Evaluation of Permanent Impairment Overview).
The rating itself does not equal your settlement, a 15% rating does not mean 15% of some amount. It is one piece of evidence supporting claims for future medical care and lost earning capacity.
Request that your physician document the basis for the impairment rating. Knowing which specific findings led to the rating helps explain it to the insurance company.
Independent Medical Examination in Personal Injury Cases
Insurance companies often request an independent medical examination (IME), an exam by a doctor hired and paid by the insurer, so it is not truly independent. IME doctors often conclude your injury is less severe than your treating physicians say. Prepare: bring all medical records, your symptom journal, and documentation of functional limitations, and be honest and consistent. Afterward, request the report, review it carefully, and document any errors or missed findings your attorney can challenge.
At Cummings Law, we prepare clients for IMEs and challenge unfavorable findings. Proper preparation and aggressive follow-up protect your case value.
Calculating Permanent Injury Settlement Value
Settlement value has three main components: past medical expenses, future medical expenses, and non-economic damages. The difference between a demand insurers take seriously and one they discount is usually the quality of the future-loss evidence, not the size of the past bills.
Past and future medical expenses
Past medical expenses are straightforward: collect all bills and receipts, ER visits, hospital stays, surgery, therapy, medications, and reconcile the totals against your insurer’s explanation of benefits. Future medical expenses are trickier: you must prove ongoing care is needed because of the permanent injury, so get your physician’s estimate of future treatment needs, including frequency and duration.
A life-care plan is a detailed document listing all anticipated future medical care and costs. It typically includes physician visits, therapy, medications, medical equipment, home modifications, and attendant care, each with a frequency and a unit cost.
Lost wages and future lost income
Document all wages lost due to the injury, including time off for treatment and recovery. Have your employer confirm days and wages missed, and gather pay stubs, tax returns, and overtime or bonus records showing your actual earnings history.
A vocational assessment evaluates your ability to work given your permanent limitations. A vocational expert examines your education, work history, and current restrictions, and identifies the occupations you can still perform. The expert then compares the earnings in those occupations with what you earned before the injury.
If you earned $60,000 before the injury and can now only earn $40,000 due to permanent restrictions, the difference is recoverable. Over a working lifetime, this is substantial.
Non-economic damages and quality of life
Non-economic damages compensate for pain, suffering, and reduced quality of life. They have no receipt and are harder to prove but often the largest part of a settlement. Document how the injury affects daily life, lost hobbies, chronic pain, relationship strain, depression or anxiety. Keep a quality-of-life journal describing activities you miss and emotional impact, and include family statements about changes they’ve observed; this gives your attorney concrete examples for negotiation.
Distinguishing impairment ratings from legal damages
An impairment rating is a medical finding, not a damages formula. A 15% impairment rating does not translate into 15% of any settlement figure. Settlement value depends on causation, the documented past and future losses, the non-economic impact, and the rules that apply to your claim. The rating is one input that supports the permanence conclusion; the dollar value comes from the loss evidence described above.
Future-loss projections are only as strong as their assumptions. A life-care plan or vocational report that relies on unsupported guesses about your condition or earnings will be attacked. Make sure every assumption is tied to a medical record, an earnings document, or a treating physician’s recommendation.
Common Mistakes to Avoid When Proving Permanence
One major mistake is delaying treatment, insurers argue the injury is not serious, so seek immediate medical attention after an accident.
Proving permanent impairment requires thorough medical documentation, clear evidence of functional limitations, and careful calculation of lifetime impact, the quality of your proof often separates a low settlement from fair compensation.
At Cummings Law, we build strong cases by gathering comprehensive medical evidence, documenting real-world impact, and challenging insurance company tactics. We operate on contingency, meaning you pay no fees unless we win.
If you have suffered a permanent injury due to someone else’s negligence, call Cummings Law for a consultation. Let us show you how to prove your case and recover the compensation you deserve.
Frequently Asked Questions
What is the difference between an impairment rating and a settlement amount?
An impairment rating documents the extent of lasting loss of function caused by your injury, but it does not automatically determine your settlement value. The rating is one piece of evidence that helps substantiate your permanent impairment claim. Your actual settlement depends on multiple factors: past and future medical expenses, lost income, earning capacity reduction, pain and suffering, and the specifics of your case. Insurance companies and courts consider the impairment rating alongside all other damages to calculate fair compensation.
What medical evidence do I need to prove permanent impairment?
Strong medical evidence includes diagnostic imaging (MRI, CT scans, X-rays), physician documentation of diagnosis and prognosis, treatment history, functional limitation assessments, and objective clinical findings. Your physician’s detailed notes about your condition, restrictions, and expected long-term effects are critical. Medical records showing ongoing treatment and lack of improvement over time strengthen your case.
How do I document functional limitations to support my claim?
Keep a detailed record of how your injury affects daily activities, work performance, and quality of life. Document specific restrictions: inability to lift certain weights, limited range of motion, pain levels at different times, activities you can no longer perform, and work modifications required. Include dates, circumstances, and impact on your life. Photographs of mobility aids or home modifications, and testimony from family or coworkers about observed limitations, all strengthen documentation of long-term functional effects.
Can I still file a claim if my injury happened several months ago?
Timing depends on your jurisdiction’s statute of limitations for personal injury claims. Most states allow several years to file, though the exact deadline varies. If you have already been managing your case alone, consulting with an attorney promptly is important to preserve evidence, meet filing deadlines, and ensure proper documentation. An attorney can review whether you have taken steps that might affect your claim and advise on next actions. Do not delay further, contact a legal professional to understand your specific timeline and protect your rights.