Table of Contents
- How Pre-Existing Conditions Affect Your Personal Injury Claim
- Insurance Adjuster Tactics for Pre-Existing Conditions
- Eggshell Plaintiff Rule Explained: You Take Your Victim as You Find Them
- How to Prove Aggravation of a Pre-Existing Injury
- The Role of Digital Health Records and HIPAA in Your Claim
- How Pre-Existing Conditions Affect Different Types of Accidents
- How Settlements Are Calculated When You Have Pre-Existing Conditions
- What to Do If an Insurance Company Denies Your Claim
- Frequently Asked Questions
Last Updated: October 1, 2026
How Pre-Existing Conditions Affect Your Personal Injury Claim
A pre-existing condition is any injury or illness you had before the accident, and insurers treat it as a discount on your case, not a disqualifier, a ready-made argument that your pain was already there.
Insurance Adjuster Tactics for Pre-Existing Conditions
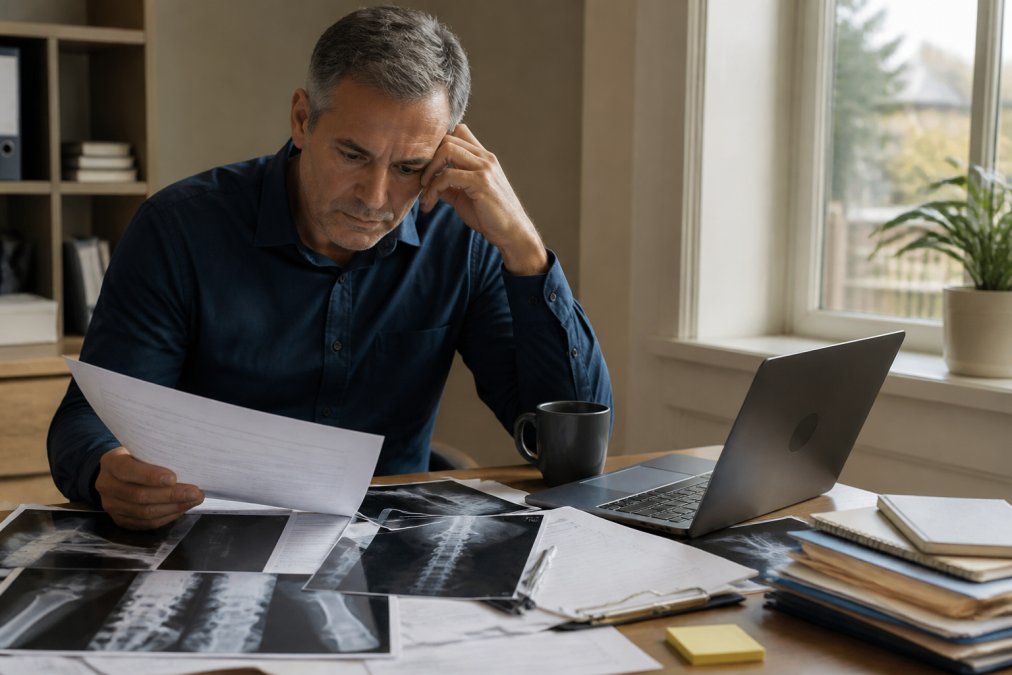
Insurance adjusters use pre-existing conditions as a primary defense to argue that current pain stems from an earlier issue rather than the accident, aiming to minimize financial liability, according to attorney Don Marcari’s overview of insurance defense strategies. Expect three moves.
The Pre-Existing Condition Defense Strategy
The insurer argues proximate cause: the accident did not actually cause your current condition. If your records show a 2019 back injury and a 2026 crash, the adjuster claims the crash merely revealed old damage.
Why Insurers Scrutinize Your Medical History
Your medical history is the adjuster’s roadmap: every prior diagnosis, imaging result, and prescription becomes a data point used to reduce settlement value. Never hand over records without guidance from a lawyer.
Eggshell Plaintiff Rule Explained: You Take Your Victim as You Find Them
The eggshell plaintiff rule holds that a defendant is liable for the full extent of harm caused to a plaintiff, even if a person with a normal constitution would have suffered less. If your pre-existing condition makes the injury far worse than expected, the driver still pays for the harm they caused.
The eggshell plaintiff rule applies to physical vulnerabilities and, in many jurisdictions, psychological ones. If the accident worsened an existing anxiety or PTSD condition, that harm can be compensable too. Ask your attorney whether your mental health history fits the doctrine.
How to Prove Aggravation of a Pre-Existing Injury
Proving aggravation of injury means showing your condition measurably worsened because of the accident. Legal strategies now focus heavily on documenting this aggravation, according to Trivent Legal’s guidance on aggravation claims, because it is the difference between a denied claim and a full recovery.
Medical Records and Diagnostic Imaging
Pre-accident health records establish your baseline, while diagnostic imaging (MRIs, CT scans) shows objective changes like new disc herniation or ligament damage. Get imaging promptly; a gap of months weakens causation.
Expert Witness Testimony
An expert witness, often a physician, reviews your records and testifies that the accident aggravated your condition, testimony that carries real weight with adjusters and juries. Retaining an expert early, rather than waiting for litigation, shapes the medical narrative from day one.
| Proof Type | What It Shows | Best Timing |
|---|---|---|
| Pre-accident records | Your baseline health | Immediately |
| Diagnostic imaging | Objective new damage | Within weeks |
| Expert witness | Causation link | Before settlement talks |
The Role of Digital Health Records and HIPAA in Your Claim
Digital health records make your medical history easier to obtain, which cuts both ways. Insurers can pull years of data quickly, but so can your attorney. The U.S. Department of Health and Human Services guidance on HIPAA governs how your records are shared and protects against unauthorized disclosure.
How Pre-Existing Conditions Affect Different Types of Accidents
The impact of a prior condition varies sharply by accident type, and defense tactics shift accordingly.
Car Accident Claims
Rear-end and side-impact crashes produce soft-tissue injuries that are easy to attribute to old problems. Insurers lean hard on prior neck and back complaints. Prompt imaging and consistent treatment are your best counter.
Slip and Fall Claims
Fall cases often involve pre-existing knee or hip conditions. The defense argues you were already unstable. Witness statements and incident reports documenting the fall mechanism help establish that the property owner’s negligence caused the worsening.
Medical Malpractice Claims
Here, your prior condition is often the reason you sought care. The question becomes whether the provider’s negligence worsened your chronic condition or caused new harm. These cases hinge on medical documentation and expert review.
How Settlements Are Calculated When You Have Pre-Existing Conditions
Settlements with prior injuries start from the same building blocks as any claim: medical expenses, lost wages, pain and suffering, and future care. The pre-existing condition affects one variable above all: causation, how much of your current condition is attributable to the accident versus your baseline.
The Apportionment Math, Step by Step
Say your pre-accident baseline was a manageable back issue that flared a few times a year. After the crash, you have constant pain, new radiating symptoms, and a disc herniation on imaging. The adjuster will not pay the full value of your current condition; they will argue a percentage belongs to the old injury.
- Objective change on imaging. A new herniation, a new tear, or a new nerve impingement that was not present on prior imaging is the single most persuasive fact. It is hard for an adjuster to attribute a brand-new finding to an old condition.
- A documented baseline. If your pre-accident records show you were functioning at a certain level, working, exercising, sleeping through the night, that baseline becomes the floor the insurer must argue above.
- Consistency of treatment. Gaps in care are read as evidence the injury was not serious. Continuous treatment from the date of the accident forward closes that argument.
Why Maximum Medical Improvement Matters to the Number
Maximum medical improvement (MMI) is the point at which your condition has stabilized and further treatment is unlikely to improve it. Reaching MMI gives both sides a stable number to negotiate around; before MMI, the insurer can argue your future care costs are speculative, and any settlement you sign is final, you cannot come back for more if your condition worsens.
A Simple Way to Estimate Your Reduction
No two cases are identical, but you can pressure-test your claim with four numbers:
- Your total current medical expenses related to the accident.
- The portion of those expenses a reasonable adjuster could tie to your pre-existing condition.
- Your lost wages attributable to the accident.
- A pain and suffering figure, which is typically a multiple of your economic damages and varies widely by jurisdiction and injury severity.
Ask your attorney whether your jurisdiction follows a pure apportionment rule or a more plaintiff-friendly standard. The rule that applies in your state can change the outcome more than any single piece of evidence.
Where the Insurer’s Discount Usually Comes From
Insurers rarely announce a percentage. They build the discount into a low initial offer, justified with three arguments: the injury was degenerative, the symptoms were pre-existing, or the treatment was unrelated. Each is answerable, but only with records, a demand letter walking through your baseline, post-accident imaging, and your treating physician’s causation opinion is what forces the number up.
What to Do If an Insurance Company Denies Your Claim
A denial of coverage is not the end of your case, often it is an opening negotiating position. The sequence that protects your rights:
- Request the denial in writing with the specific reason cited
- Pull your complete pre-accident and post-accident medical records
- Get an independent medical evaluation if the insurer disputes causation
- Preserve the accident report, witness contacts, and any photos
- Consult a personal injury attorney before speaking to the adjuster again
- File suit before the statute of limitations expires, if negotiation stalls
The Denial Reason Tells You the Counterattack
Read the denial letter closely: the stated reason usually falls into one of four buckets, each with a different response.
- “No liability.” The insurer disputes that its policyholder caused the accident. This is a liability fight, not a medical one, and it is won with the police report, witness statements, and scene evidence.
- “Causation.” The insurer admits the accident happened but blames your pre-existing condition. This is the most common denial in prior-injury cases and the one your medical records must answer.
- “Treatment gap.” The insurer argues you were not really hurt because you stopped treating. A gap has explanations, cost, referral delays, fear of providers, and those explanations belong in the record.
- “Coverage.” The policy itself does not apply, or limits are exhausted. This is a contract question, and it may mean looking at other policies, including your own uninsured/underinsured motorist coverage.
The Gap Most Guides Miss: Mental Health Pre-Existing Conditions
Almost every article on this topic focuses on bad backs, bad knees, and old neck injuries. Very few address what happens when your pre-existing condition is psychological, anxiety, depression, PTSD, or a chronic pain-related mood disorder. This matters because pain and suffering damages are a major component of many claims, and insurers routinely argue that a claimant’s emotional distress predates the accident.
- A pre-accident baseline. Mental health records, therapy notes, or a primary care history showing how you were functioning before the crash.
- A post-accident change. New symptoms, increased medication, new therapy, or a treating provider’s opinion that the accident aggravated the condition.
- A causation link. A mental health professional who can connect the accident to the worsening, the same way an orthopedist connects a crash to a disc injury.
Mental health records are sensitive, and releasing them broadly can expose unrelated history the insurer will use against you. Have an attorney review any release before you sign it, and ask whether a narrowly tailored authorization can satisfy the insurer without handing over your entire psychiatric file.
What Happens After You Push Back
Most denials soften once a lawyer sends a documented demand letter: the insurer raises its offer, withdraws the denial, or forces the case into litigation. If litigation becomes necessary, the same evidence that should have resolved the claim, baseline records, post-accident imaging, and treating providers’ opinions, becomes the foundation of your case.
Frequently Asked Questions
Can I still get a settlement if I have a pre-existing condition?
Yes, you can still recover compensation. A pre-existing condition does not disqualify you from seeking damages. The law recognizes that a prior condition can make you more vulnerable to new injuries. Insurance companies may argue that your current pain stems from the old condition, but with proper medical documentation and legal representation, you can prove that the accident aggravated your condition and recover damages for the worsening of your injury.
What is the ‘eggshell plaintiff’ doctrine in personal injury law?
The eggshell plaintiff rule holds that a defendant takes their victim as they find them. If you have a pre-existing condition that makes you more susceptible to injury, the at-fault party is still fully liable for the harm caused, even if a healthier person would have suffered less. This doctrine prevents defendants from escaping responsibility simply because you were more fragile. It ensures that you can recover full compensatory damages for your aggravated injury.
How do insurance adjusters use medical history to deny claims?
Insurance adjusters often use your past medical records to argue that your current pain is related to a pre-existing condition rather than the accident. They may claim that your injury is degenerative or that you had the same symptoms before. They look for gaps in treatment, prior injuries to the same body part, and any mention of chronic pain. Their goal is to minimize liability and reduce your settlement value.
How does an aggravation of a pre-existing condition affect compensation?
Aggravation of a pre-existing condition can increase your compensation if you can prove that the accident made your condition worse. You may recover damages for the additional pain, medical expenses, and lost wages caused by the worsening. However, you are not entitled to compensation for the pre-existing condition itself. Proving aggravation requires strong medical evidence, such as diagnostic imaging and expert testimony, to separate the old injury from the new aggravation.
An insurer will use your medical history to shrink your claim, and doing nothing lets that argument stand. Cummings Law, led by Brian Cummings, investigates thoroughly, gathers the evidence that proves aggravation, and represents you without upfront fees until your case resolves. Get started with Cummings Law and recover the compensation your injury deserves.